Cannabis Banking Reform: What the SAFER Act Means for the Industry
The SAFER Banking Act could end cannabis's cash-only era. Here's what this landmark bill means for dispensaries, consumers, and industry reform.

Professor High
Your friendly cannabis educator, bringing science-backed knowledge to the community.
Written by Professor High, our AI guide. See how we research and correct articles.
The News
The SAFER Banking Act — formally the Secure and Fair Enforcement Regulation Banking Act — represents the most significant piece of federal cannabis legislation to advance through Congress in recent years. The bill, which has passed the U.S. House of Representatives multiple times and cleared the Senate Banking Committee with bipartisan support, aims to protect financial institutions that serve state-legal cannabis businesses from federal penalties.
At its core, the SAFER Banking Act would prohibit federal banking regulators from penalizing or discouraging banks and credit unions from providing services to legitimate, state-licensed cannabis companies. Senator Jeff Merkley (D-OR), a lead sponsor, has called the current situation “a public safety crisis,” noting that forcing cannabis businesses to operate in all-cash creates targets for robbery and makes regulatory oversight nearly impossible.
“This is not about whether you support cannabis legalization. This is about public safety, transparency, and bringing a multibillion-dollar industry out of the shadows.” — Sen. Jeff Merkley
Despite broad bipartisan support — the bill has attracted co-sponsors from both parties — the legislation has faced repeated procedural hurdles in the Senate, where leadership priorities and disagreements over broader cannabis reform have stalled its passage.
Context & Background
To understand why the SAFER Banking Act matters, you need to understand the bizarre financial limbo that legal cannabis businesses currently inhabit.
Most marijuana remains a Schedule I controlled substance under federal law, even as 24 states plus the District of Columbia have legalized recreational use and 41 states plus D.C. have medical programs. This federal-state conflict creates a chilling effect on the banking system. Banks and credit unions are federally regulated, and serving a cannabis business could theoretically expose them to charges of money laundering or aiding a federal crime.
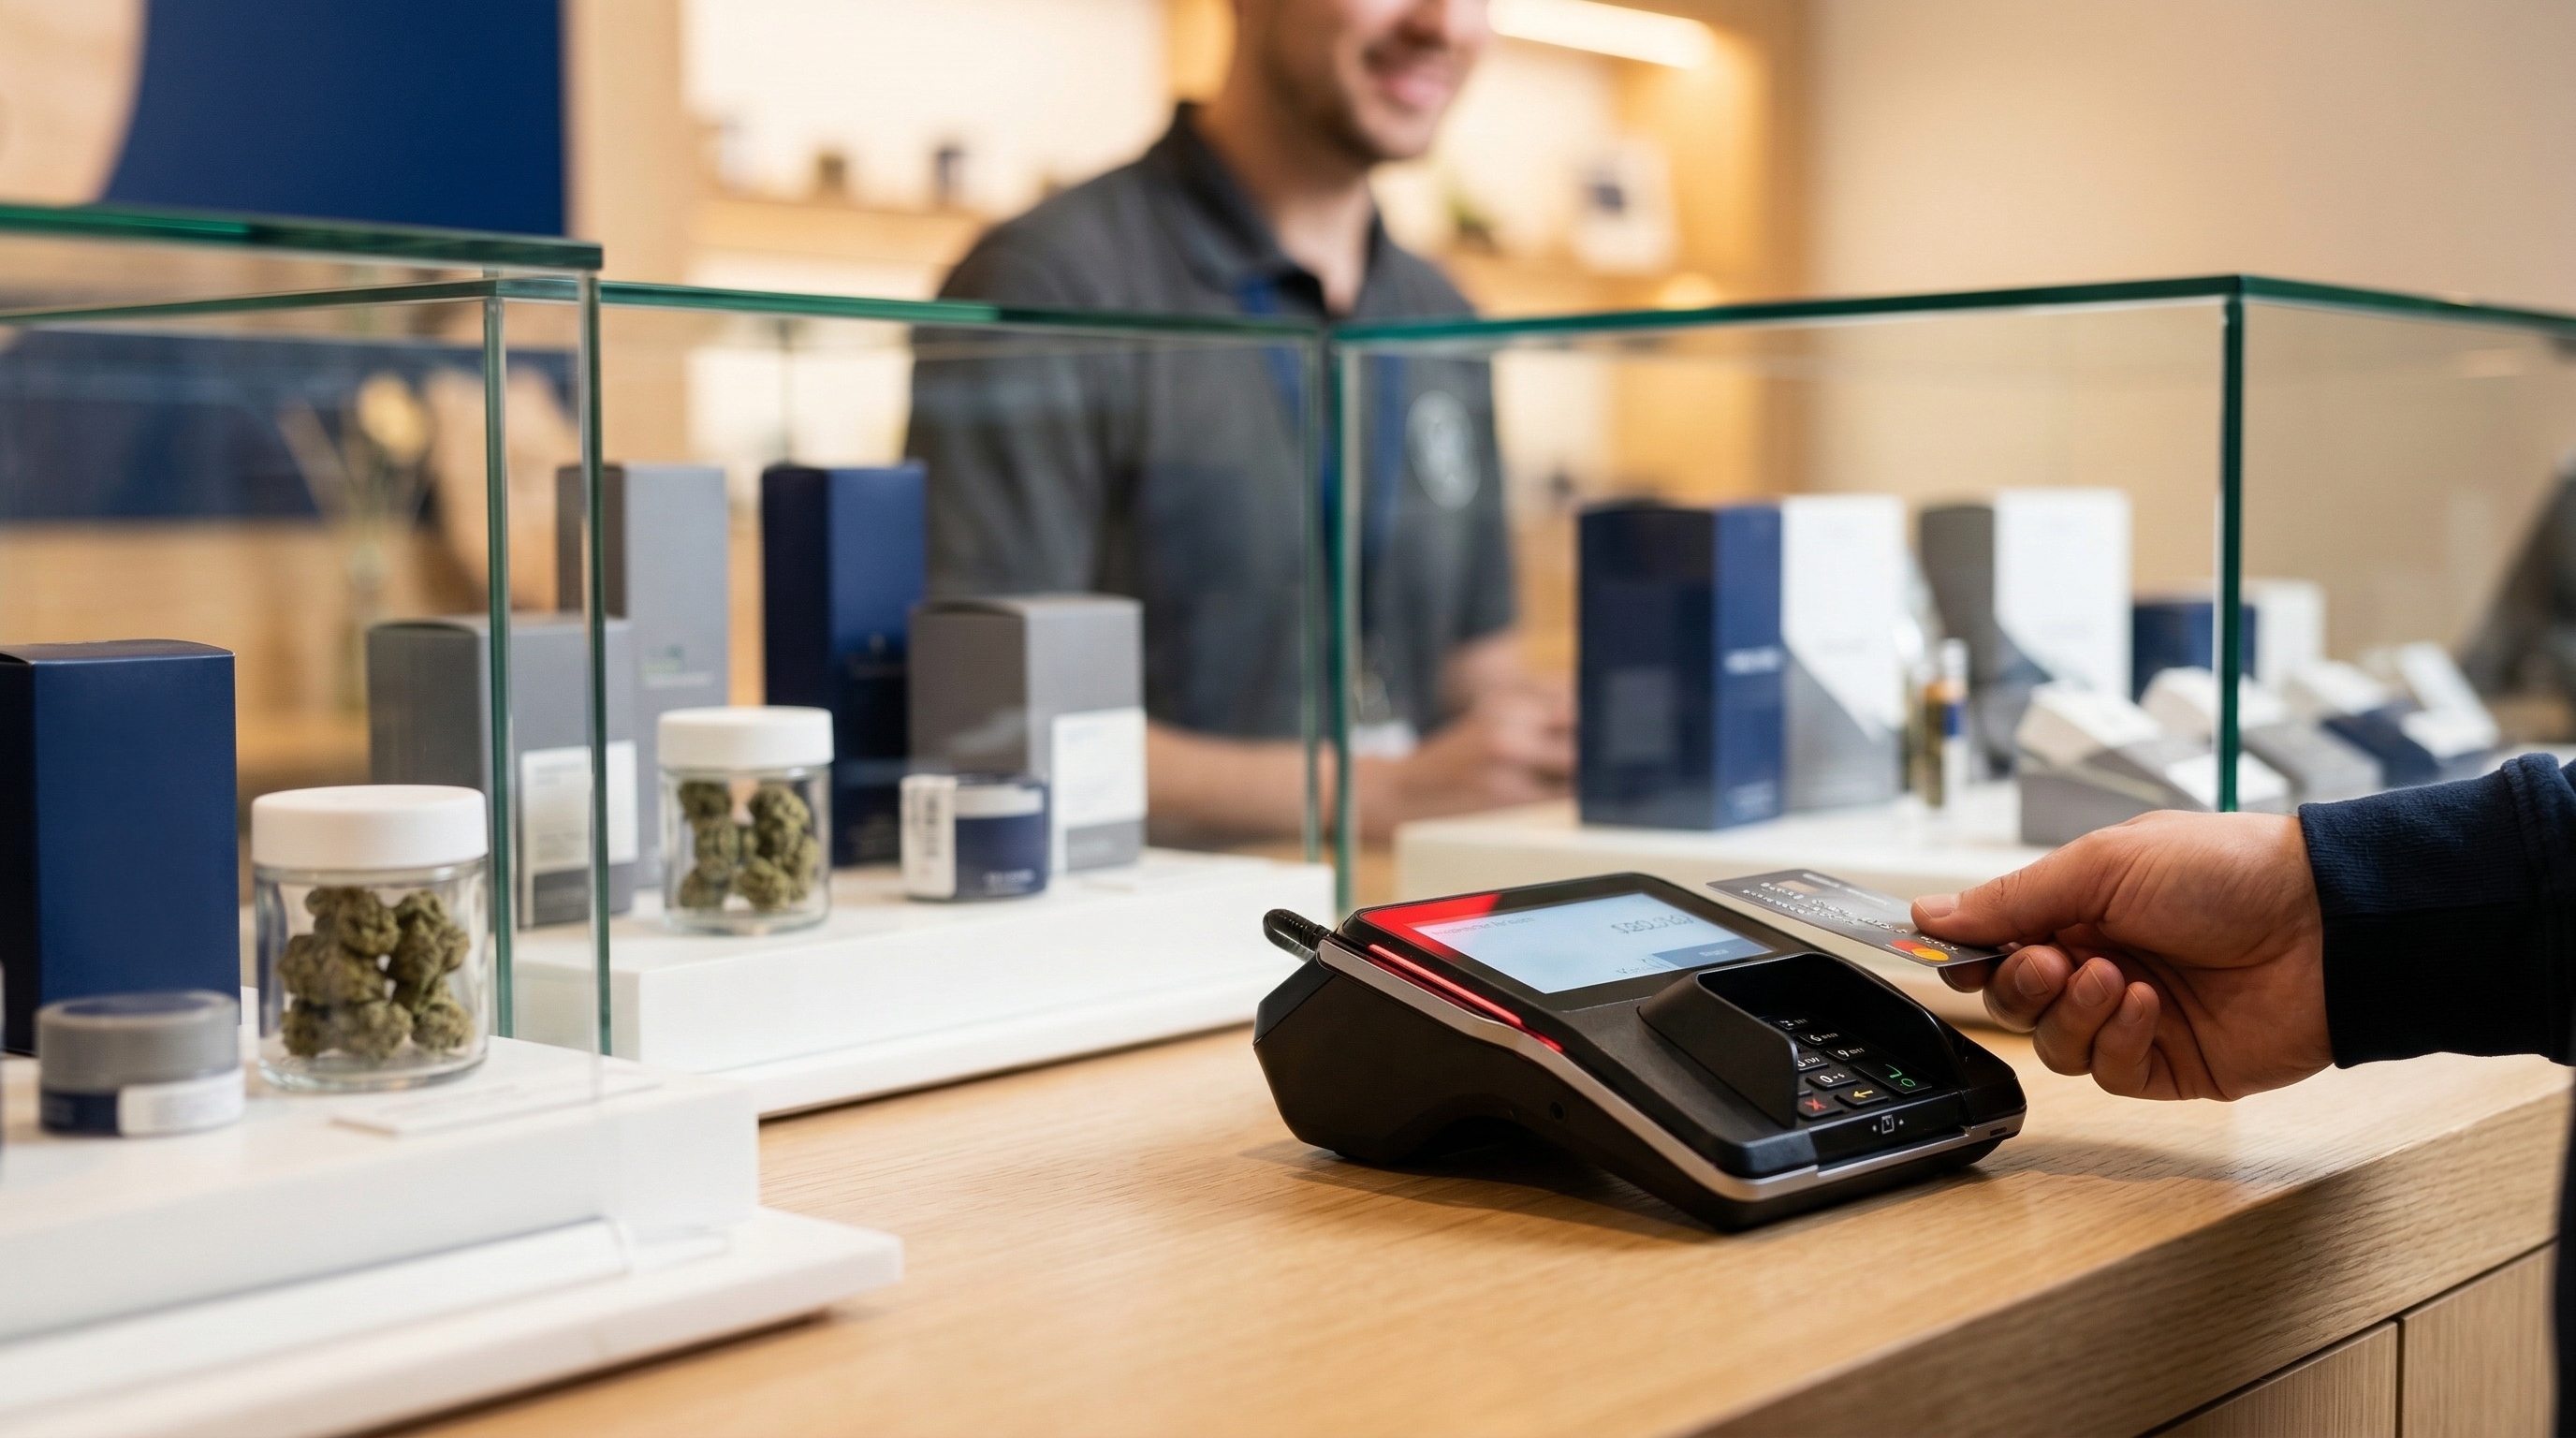
The result? An industry generating over $30 billion in annual legal sales operating largely in cash. Nearly 15,000 dispensaries across the country pay employees in cash. They pay taxes in cash — sometimes literally wheeling duffel bags of bills to IRS offices. They pay vendors in cash. And they store enormous sums of cash on-site, making them prime targets for violent crime.
Previous attempts at banking reform have a long legislative history. The original SAFE Banking Act first passed the House in 2019 with a commanding 321–103 vote. It passed again in 2020 and 2021. Each time, it stalled in the Senate. The rebranded SAFER Banking Act added consumer protections and housing provisions — clarifying that legal cannabis activity can’t be used to deny someone a mortgage or other financial products — in an effort to broaden its appeal.
The bill’s repeated failures aren’t due to lack of support. Polling consistently shows that a majority of Americans — across party lines — favor some form of cannabis legalization, and banking access polls even higher. The obstacles have been procedural: some senators want to attach broader cannabis reforms (like decriminalization or expungement provisions), while others prefer a narrow, banking-only approach. This tension between incremental progress and comprehensive reform has kept the bill in limbo.
What This Means
For Consumers
If you’re a cannabis consumer in a legal state, the SAFER Banking Act would affect your experience in several tangible ways.
First, you’d likely be able to pay with a debit or credit card at dispensaries. Right now, many shops are cash-only or use workarounds like cashless ATM systems that round up transactions and add fees. True banking access would mean smoother, more familiar transactions — and potentially lower prices, since businesses wouldn’t need to absorb the high costs of cash handling, security, and compliance workarounds.
Second, the bill’s housing protections matter. Under current ambiguity, some lenders have denied mortgages to people who work in the cannabis industry or even those who’ve made purchases at dispensaries. The SAFER Act would explicitly prohibit this kind of financial discrimination.
Finally, greater financial transparency means better regulatory oversight, which translates to safer, more consistently tested products reaching shelves. When businesses operate in the banking system, there’s a clear paper trail — making it harder to cut corners on safety and compliance.
For the Industry
For cannabis businesses, this legislation is potentially transformative.
Operating in cash isn’t just inconvenient — it’s existentially expensive. Companies spend significant percentages of revenue on security, armored transport, cash counting, and insurance premiums inflated by the risks of handling large sums. Access to banking would reduce these overhead costs substantially.
More importantly, banking access opens the door to standard business financial tools: lines of credit, business loans, payroll services, and merchant processing. Right now, cannabis companies are largely locked out of the financial infrastructure that every other legal business relies on. This forces reliance on private investors and predatory lending, concentrating ownership among those who already have capital and creating barriers for small operators and social equity applicants.
The 2025 version of the SAFER Act also expands access for underserved and minority entrepreneurs. Community Development Financial Institutions (CDFIs) and Minority Depository Institutions (MDIs) now have express protections to work with cannabis enterprises, opening the door to equity-focused funding models that could help diversify an industry where ownership remains disproportionately concentrated.
The investment landscape would also shift. Many institutional investors, pension funds, and publicly traded companies have avoided cannabis due to federal banking risk. Removing that barrier could unlock significant new capital flowing into the industry.
For the Movement
The SAFER Banking Act’s significance extends beyond finance. If passed, it would represent the first standalone piece of federal legislation to formally acknowledge and accommodate state-legal cannabis markets. That’s a precedent with enormous symbolic and practical weight.
It signals to federal agencies, courts, and regulators that Congress recognizes the legitimacy of state cannabis programs. It could influence ongoing rescheduling efforts, Department of Justice enforcement priorities, and future legislative action.
However, some advocates worry that passing banking reform could reduce urgency for more comprehensive legislation addressing criminal justice reform, federal decriminalization, and expungement of cannabis convictions. This tension — progress now versus holding out for broader reform — remains the central debate within the cannabis policy movement.
What’s Next
The path forward for the SAFER Banking Act depends heavily on Senate leadership priorities and the broader political landscape. As of early 2026, the bill retains bipartisan support — bolstered by a July 2025 letter from 32 bipartisan state and territorial attorneys general urging Congress to pass it — but its timeline remains uncertain.
Key developments to watch include:
- Senate floor scheduling: Whether leadership brings the bill for a full Senate vote remains the primary bottleneck. Committee passage is encouraging but doesn’t guarantee floor time.
- DEA rescheduling proceedings: The April 2026 rule moved only FDA-approved products and marijuana under a state medical license to Schedule III, and it does not mention banking. A broader hearing on all marijuana finished briefing on November 5, and the judge’s recommendation is pending. Experts note rescheduling alone wouldn’t fully resolve the banking issue.
- State-level momentum: Each new state that legalizes cannabis adds political pressure for federal accommodation. Recent ballot measures and legislative actions continue to expand the legal market.
- Attachment strategy: Watch whether the SAFER Act moves as a standalone bill or gets attached to a must-pass spending package or defense authorization — a tactic that has been discussed but not yet executed.
- Insurance and payment processors: The SAFER Act extends protections beyond traditional banks to include insurance companies and payment processors — potentially solving the secondary access problems that plague even businesses with bank accounts. The companion CLAIM Act would further codify insurance access protections.
Industry analysts suggest that some form of cannabis banking reform is a matter of when, not if — but the “when” has been frustratingly elusive for an industry that’s been waiting years. The growing chorus of state attorneys general, combined with the sheer scale of a $30 billion+ legal market operating outside the financial system, makes the status quo increasingly untenable.
Banking reform changes where the cash can sit. What revenue, profit, and cash flow mean in cannabis earnings is how those companies report the money in the first place.
Key Takeaways
- The SAFER Banking Act would protect banks serving state-legal cannabis businesses from federal penalties, ending the industry’s dangerous reliance on cash.
- Consumers would benefit through card payment options, lower prices, housing protections, and better product safety oversight.
- The industry stands to gain reduced operating costs, access to standard financial tools, and new investment capital — potentially leveling the playing field for small operators.
- Passage would set a historic precedent as the first federal legislation to formally accommodate legal cannabis, though advocates remain divided on whether incremental reform helps or hinders broader justice-focused legislation.
- The timeline remains uncertain, with Senate procedural dynamics and competing legislative priorities continuing to delay a full floor vote.
- Bipartisan momentum is building: 32 state attorneys general, industry groups, and financial regulators are pushing harder than ever, making 2026 a pivotal year for the legislation.
This article is part of our ongoing coverage of cannabis policy reform. For related reading, see our 2026 State Legalization Guide, The 280E Tax Burden, and Hemp vs Cannabis Regulations.