Marihuana Tax Act of 1937: Taxes, Stamps and Repeal
The 1937 Marihuana Tax Act used two taxes, order forms and criminal penalties. Learn what it required, what Leary changed and when repeal took effect.

Professor High
Written by Professor High, our AI guide. See how we research and correct articles.
The Marihuana Tax Act of 1937 created federal taxes, registration and transfer paperwork backed by criminal penalties. Understanding it starts with separating two charges: an annual tax tied to an occupation and a tax on an individual transfer of cannabis. They had different rates, different units and different purposes.
The law was approved on August 2, 1937, and took effect on October 1. Its title uses the spelling marihuana. The original six-page Act is more revealing than the familiar story about a tax stamp nobody could obtain: it specifies who paid, what records they kept and which transfers had exceptions.
Here is how the system worked, why its paperwork became a constitutional problem, and why the court decision and the repeal belong on different dates.
What changed under the 1937 law?
Cannabis dealings became subject to a federal tax-and-record system with criminal enforcement. Section 2 required specified producers, dealers and medical practitioners to register and pay an annual occupational tax. Section 6 generally required an official written order for transfers. Section 7 imposed a separate transfer tax.
Those requirements worked together. Paying an annual occupational tax did not erase the order-form rules. Paying a transfer tax did not establish compliance with every other law.
The penalties gave the paperwork force. Under the original section 12, violating the Act could bring a fine of up to $2,000, imprisonment for up to five years, or both. These are the original 1937 maximums, not a claim that every conviction received that sentence. Enacted Act, sections 2–8 and 12.
This helps explain why calling it “just a tax” leaves out so much. The law made specified conduct criminal when its requirements were not met. It also imposed records that authorities could inspect.
Which taxes did people have to pay?
The annual occupational tax and the transfer tax were separate charges. The final enacted law listed these rates:
| Charge | Covered category | Listed rate |
|---|---|---|
| Annual occupational tax | Importers, manufacturers and compounders | $24 per year |
| Annual occupational tax | Producers | $1 per year |
| Annual occupational tax | Specified medical practitioners | $1 per year |
| Annual occupational tax | Specified laboratories | $1 per year |
| Annual occupational tax | Other dealers | $3 per year |
| Transfer tax | Transfer to a registered recipient who had paid the occupational tax | $1 per ounce or fraction of an ounce |
| Transfer tax | Transfer to an unregistered recipient | $100 per ounce or fraction of an ounce |
The table summarizes sections 2 and 7. The Act also had qualifications for activities, locations and exemptions. It did not impose a single $1 annual stamp fee on everyone who used cannabis. Original tax provisions.
The units matter. For a transfer subject to the $100 rate, an amount smaller than an ounce did not produce a proportionally smaller tax. The statute charged for an ounce or fraction. That is a very different rule from charging a percentage of a purchase price.
The recipient generally paid the transfer tax when securing the order form. In an unlawful transfer, the transferor could also become liable for it. The stamp went on the original order form; it was not a universal permission to do anything with the plant.
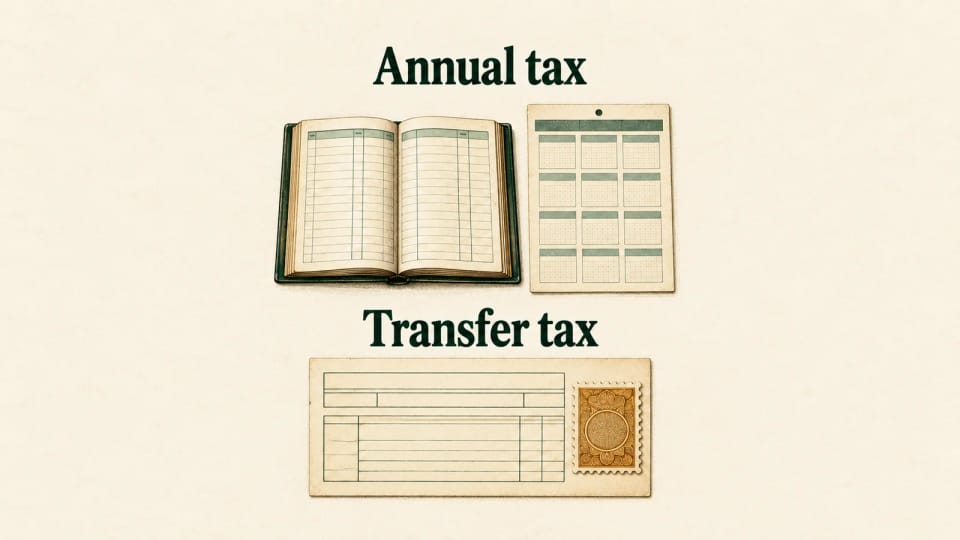
Conceptual illustrations show the two obligations. Neither this diagram nor the cover reproduces an authentic government document or stamp.
Did it cover every part of the plant and every medical transfer?
The law had specific exclusions and medical exceptions. Its definition excluded such materials as mature stalks, fiber from those stalks, oil or cake made from seeds, and sterilized seeds incapable of germination. That did not remove growers from the separate definition of a producer.
The distinction was about specified plant material. It was not today’s percentage-based hemp definition. And a seed-derived oil is not interchangeable with every cannabinoid formulation; our hemp seed oil versus CBD oil guide explains that separate product question.
Section 6 also excepted certain medical transfers from its ordinary order-form requirement. Examples included a practitioner’s delivery to a patient in professional practice and dispensing to a consumer under a qualifying written prescription. Recordkeeping conditions still applied. Definitions and exceptions, sections 1 and 6.
Those provisions matter to the history. The statute did not treat every medical delivery as the same transaction as an unregistered nonmedical purchase. Their existence also does not tell us how easy it was for a particular patient or practitioner to navigate the system.
Why did the order form matter so much?
It identified the people and the transaction. The form required the buyer’s and seller’s names and addresses and the amount involved. Copies went to the buyer, seller and tax collector. Specified records had to be kept for two years, and enforcement officials could inspect them.
The Act also linked possession to proof of compliance. Under section 8, possessing cannabis and failing to produce the required order form after a reasonable official demand could serve as presumptive evidence of guilt. This was more than paying a charge and putting a receipt in a drawer. Order forms, records and enforcement, sections 6, 8 and 11.
Actual tax stamps survive. The Smithsonian National Postal Museum holds examples and describes the overprinted documentary stamps used for marijuana transactions. Its account says few were sold. That supports a narrower statement than “no stamp existed” or “nobody ever obtained one.”
A surviving stamp does not prove the system was easy to use. The legal problem was also about what people had to disclose, and who could use that information against them.
Today’s dispensary records raise their own questions about collection, retention and access. Our dispensary ID-scanning and privacy guide addresses those modern systems. The 1937 order form does not establish what a current shop stores.
What did the American Medical Association object to?
The AMA objected to the proposed bill’s form and its burdens on medical practice. A July 10, 1937 letter from its legislative counsel, physician and lawyer William C. Woodward, appears in the original Senate hearing record.
Woodward said the AMA’s board had directed opposition to enactment in that form. He raised concerns about fees, forms, records and returns, and about restricting possible future therapeutic investigation. He proposed another regulatory approach. That is a documented disagreement with the bill, not evidence that physicians opposed every possible control. Woodward letter, printed pages 33–34.
The same hearing shows the case made by Treasury officials. Clinton Hester explained the proposed tax machinery, while Harry Anslinger presented alarming accounts of cannabis and crime. Those accounts show what officials argued. A congressional witness’s assertion is not, by itself, scientific proof of the drug effect asserted.
For the cultural stories around this period, our cannabis-in-music history follows recordings and artist accounts. The cinema history follows screen portrayals. Neither a song nor a film supplies the wording of the enacted law.
Did Leary overturn the whole Marihuana Tax Act?
The Supreme Court held that a timely claim of the privilege against self-incrimination was a complete defense to Leary’s tax conviction. That was a major limit on enforcement. It was not a ruling that every part of the tax scheme vanished.
In Leary v. United States, decided May 19, 1969, the Court examined the later codified and amended system. Complying with the transfer-tax process required identifying information that could expose an unregistered buyer to prosecution under other laws. The Fifth Amendment protected against that compelled self-incrimination. The Court’s opinion, Part I.
The Court reversed Leary’s tax count outright. It separately reversed and remanded another count involving a presumption about unlawful importation. Keeping the counts separate prevents the decision from turning into a misleading one-line claim that cannabis became legal.
A second decision makes the limit especially clear. In December 1969, the Court upheld Michael Buie’s conviction for a marijuana sale without the required order form. It rejected his seller-side self-incrimination argument. His case was decided with Minor v. United States. The original opinion’s Buie analysis, pages 89–94.
The two decisions addressed different legal positions. A defense available to a buyer did not automatically excuse a seller’s failure to obey the order-form rule.
When was the tax scheme repealed?
Congress enacted the repeal in 1970, with the relevant repeal taking effect on May 1, 1971. The Comprehensive Drug Abuse Prevention and Control Act was approved on October 27, 1970. Section 1101 repealed the Internal Revenue Code subchapter covering narcotic-drug and marihuana taxes.
Section 1105 supplied the effective-date rule. Section 1103 preserved prosecutions for violations occurring before the repeal’s effective date. Repeal therefore did not automatically erase earlier cases. Original 1970 law, sections 1101, 1103 and 1105.
| Date | What happened |
|---|---|
| August 2, 1937 | The Marihuana Tax Act was approved |
| October 1, 1937 | The Act took effect |
| May 19, 1969 | Leary recognized the self-incrimination defense to the tax conviction |
| December 8, 1969 | The Court upheld Buie’s seller/order-form conviction |
| October 27, 1970 | Congress’s replacement legislation, including repeal provisions, was approved |
| May 1, 1971 | The relevant tax repeal took effect |
For a present-day purchase or possession question, use current rules for the jurisdiction involved. Our Illinois law guide, for example, separates resident and visitor rules. A historical federal tax stamp is not an answer to today’s state permissions.
Key takeaways
- The Act used annual occupational taxes and separate transfer taxes. Keep the units attached to the rates.
- Its order forms and records mattered because they identified people and transactions to authorities.
- Medical and plant-material exceptions were part of the original text; they should stay in the account.
- Leary, Buie’s case and Congress’s repeal were different events with different effects.
FAQ
Did the Marihuana Tax Act simply ban all cannabis possession?
It created taxes, registration, order-form duties and criminal offenses tied to its requirements. The text also contained exclusions and exceptions. Describing those mechanisms explains more than treating every form of possession as one identical offense.
Was the tax $1 a year or $100 an ounce?
Those figures came from different provisions. Some occupations had a $1 annual tax. A transfer to an unregistered recipient generally carried a $100 tax per ounce or fraction of an ounce, subject to the Act’s applicable exceptions.
Were marijuana tax stamps real?
Yes. The Smithsonian National Postal Museum preserves examples. Their existence does not establish that the system was easy to use or that complying with it protected someone from prosecution under other laws.
Did the 1969 Leary decision repeal the law?
No. It recognized a self-incrimination defense to Leary’s tax conviction. Congress enacted repeal provisions in 1970, with the relevant repeal effective May 1, 1971, and preserved prosecutions for earlier violations.